

Oil Traders Are Betting On Peace; The Clock Is Betting On $150 Crude
The biggest risk facing oil markets may not be another missile strike in the Middle East. It may be the calendar.
Since peaking near $120 in March, Brent crude has fallen back below $95 despite the fact that the Strait of Hormuz remains effectively closed, or at least severely choked, and US-Iran negotiations continue without a breakthrough. On the surface, that price action suggests traders believe diplomacy will eventually win. Underneath, however, the physical oil market may be operating on borrowed time.
The reason oil has not exploded higher back then is relatively simple. Governments and commercial operators responded to the crisis by aggressively releasing strategic reserves and drawing down inventories. Those stockpiles have acted as shock absorbers, allowing consumers to keep receiving crude even while normal supply routes remain impaired. The market solved a supply problem by consuming inventory rather than restoring supply.
That distinction is becoming increasingly important because inventories are not infinite. They buy time, but they cannot create oil. Analysts warn that the period between mid-June and mid-July could become a critical window as emergency buffers approach operational stress limits. If the Strait of Hormuz remains constrained by then, the market may be forced to deal with the underlying shortage directly.
That is where the discussion of $150 crude begins. Not because traders suddenly become more fearful, but because the physical market changes. Once emergency reserves can no longer compensate for disrupted supply flows, refiners and importers may be forced to compete aggressively for available barrels. The resulting squeeze could push prices far beyond levels justified by current market sentiment.
Ironically, none of this is visible in the chart today. Brent’s technical outlook remains surprisingly bearish for the near term. The rebound from 89.93 has been capped by 55 4H EMA, 55 D EMA and below 38.2% retracement of 115.30 to 89.93 at 99.62. Traders continue to sell rallies rather than chase them, reflecting confidence that negotiations will eventually succeed and that supply routes will normalize before inventories become a problem.
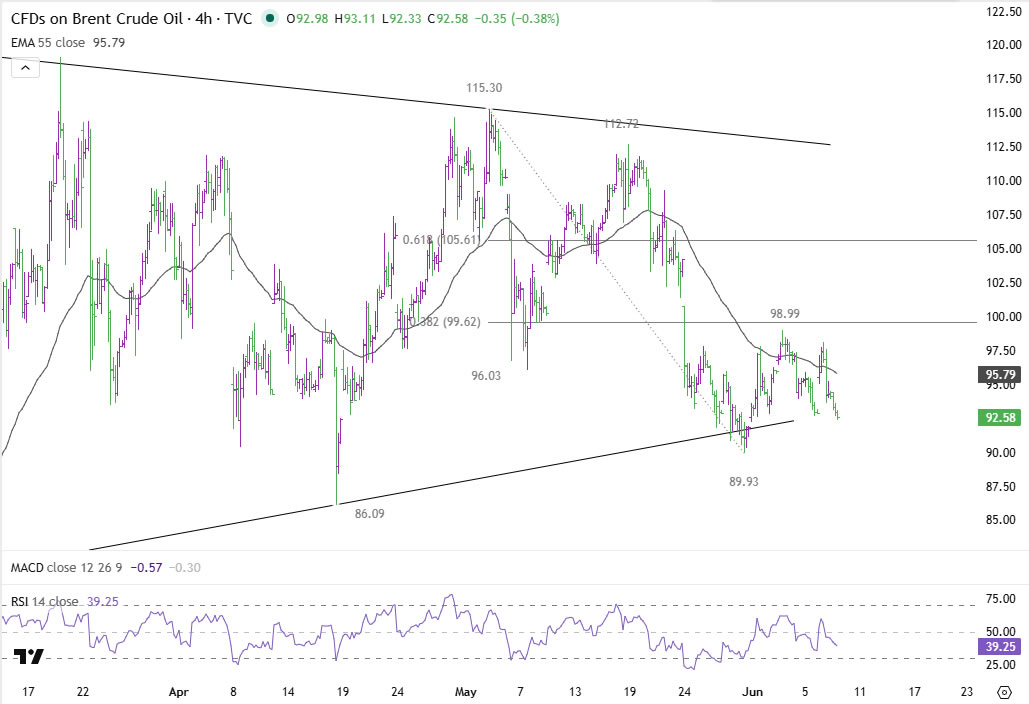
That belief leaves the downside open in the near term. A break below 89.93 would target 86.09 and potentially 61.8% retracement of 58.72 to 119.50 at 82.04. In effect, the market is still pricing peace, or at least pricing enough progress to avoid a prolonged supply crisis.
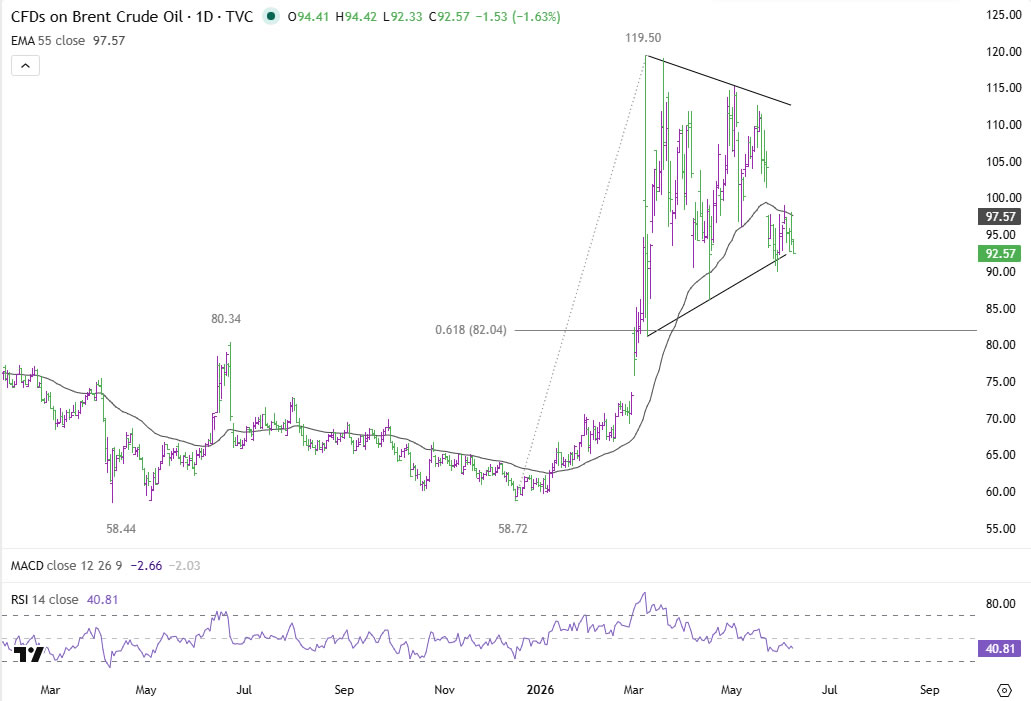
The next few weeks may reveal whether that confidence is justified. If a diplomatic breakthrough arrives before stockpiles become critically depleted, oil could continue moving lower and inflation fears would ease. If negotiations drag on while emergency reserves approach exhaustion, the market’s focus could shift abruptly from peace talks to physical shortages.
In that scenario, today’s debate over whether Brent should trade at $90 or $100 may look trivial. The real question would become whether the global economy is prepared for a world where the Strait of Hormuz remains constrained and oil is forced to reprice toward $150.
What A Rising VIX Means For Pension Funds
Wall Street’s latest selloff has moved beyond a technology-sector wobble and become a broad market event. The Nasdaq C... Read more
Behaviour Cannot Fix A Portfolio Construction Flaw
A Retiree Shouldn't Be Asked to Behave Their Way Out of a Portfolio Construction Problem Why behavioural coaching shoul... Read more
Behavioural & Retirement Portfolio Resilience
Behavioural Survivability and Retirement Portfolio Resilience Why the lived experience of market recovery matters as mu... Read more
Australia's Rate Rise Bites: Highest In 15 Years
The Reserve Bank of Australia has lifted interest rates to their highest level since 2011, and its governor admits the w... Read more
October Retirement Portfolio Resilience Assessment
Markets stabl Read more
Gyrostat September Retirement Portfolio Resilience Assessment
September Retirement Portfolio Resilience Assessment Markets have fallen. The price of risk has risen. ... Read more