
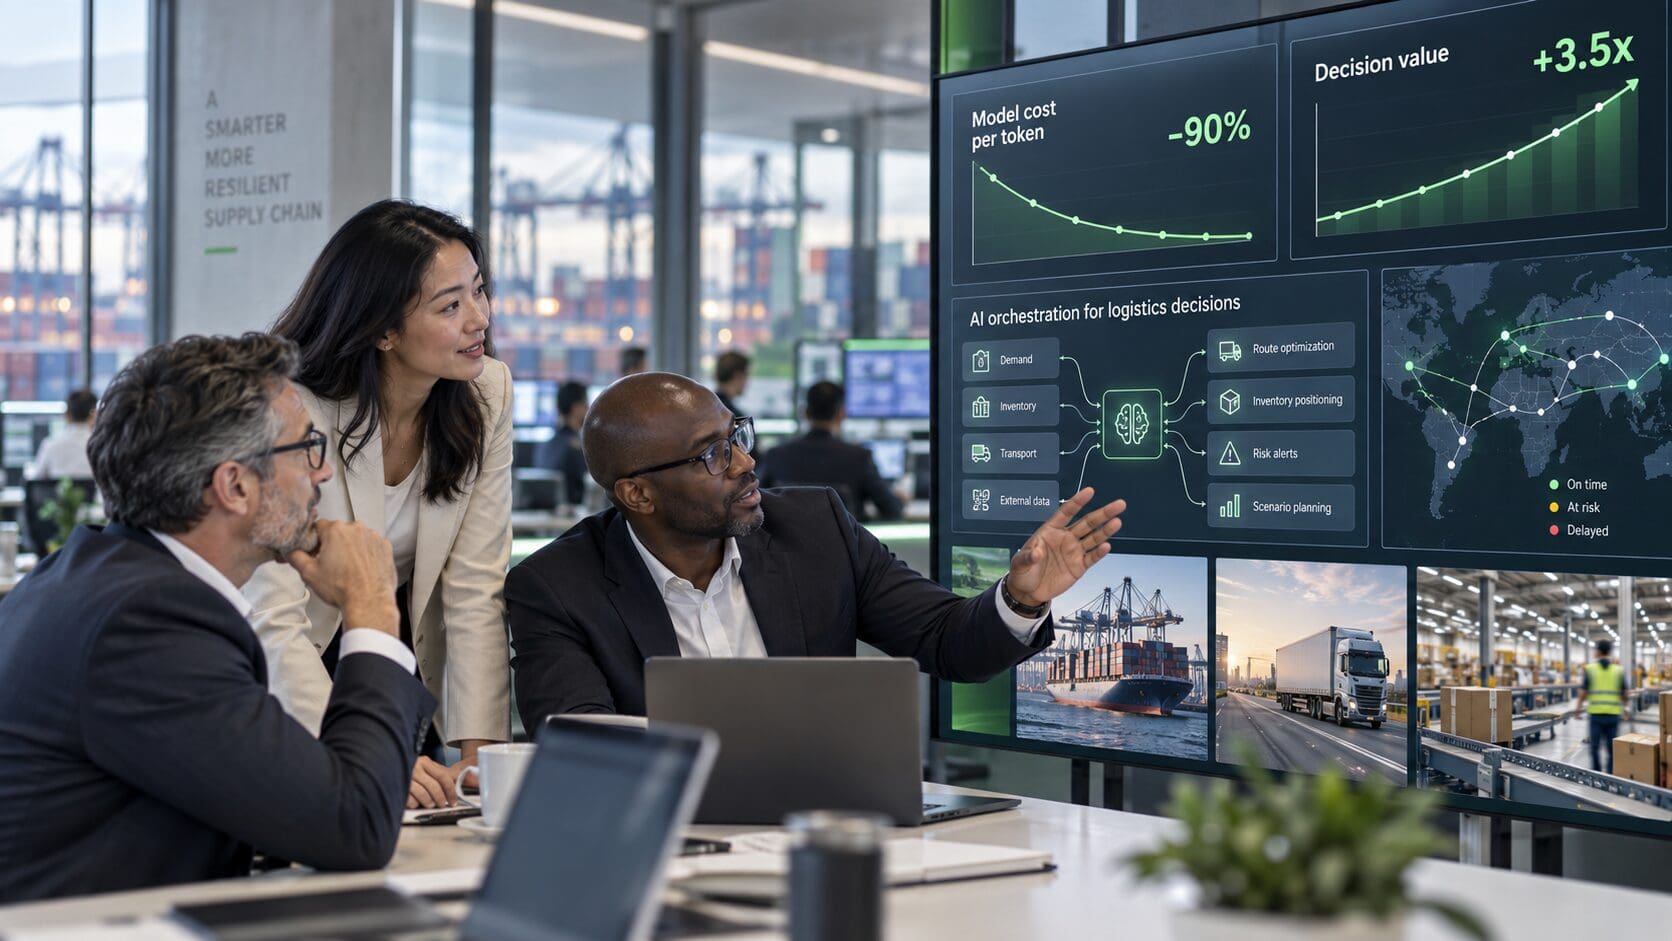
The artificial intelligence debate is changing. For several years, the central question was whether AI worked, and then whether the technology could scale. Increasingly, the more difficult question is who actually captures the value. That distinction matters because AI adoption can accelerate, token consumption can soar and the economics of individual participants can still deteriorate.
This is the point at which a technology story becomes an operating-model story. For logistics companies deciding where AI creates economic advantage, that may be much more useful than watching the daily valuation of another AI stock. The central issue is no longer simply whether AI becomes pervasive. It is how the economics of that pervasiveness are distributed across the technology stack and ultimately captured inside operating businesses.
More Tokens Does Not Automatically Mean More Revenue
The basic AI economic equation has generally seemed straightforward. Models become better, better models create more useful applications, applications increase demand and demand consumes more tokens. The assumption has often been that more tokens therefore create more revenue. The complication is price.
AI inference is becoming cheaper at a remarkable rate. Competition among model providers is increasing, open-weight models are improving, specialized models are proliferating and hardware efficiency continues to advance. That is excellent for customers, but it is less obviously excellent for every company selling tokens because rapid declines in unit pricing can offset extraordinary growth in usage.
Man Group’s bearish analysis of the AI investment cycle describes the problem starkly: if token prices decline faster than inference demand expands, enormous growth in usage does not necessarily produce the revenue required to justify an equally enormous infrastructure buildout. Goldman Sachs Research is more constructive, pointing to sharply increasing token consumption — potentially a 24-fold increase by 2030 as agentic AI expands — while declining unit compute costs could improve hyperscaler margins.
Those positions are not actually contradictory. They identify the same underlying variable from different directions. The economic outcome depends on the relationship among volume, price and cost. In other words, the AI trade is increasingly becoming a unit-economics problem.
The De-Rating Is Telling Us Something
The financial market has already become more discriminating about AI exposure. A recent Goldman basket analysis reportedly showed an all-inclusive AI pair roughly 46 percent below its previous highs, even as underlying demand for compute remains strong. Goldman’s argument is not that AI is ending; rather, the opportunity may be broadening toward businesses with clearer monetization, embedded workflows and more defensible economic positions.
That distinction is important because a broad technology transition does not guarantee that every participant in the technology stack earns extraordinary returns. The internet changed the world, yet many internet companies disappeared. Containerization transformed global trade without guaranteeing exceptional margins for every shipping line, and cloud computing became foundational infrastructure while much of the economic power concentrated in particular layers of the stack.
AI is likely to behave similarly. The technology can be revolutionary while the value migrates, and investors are beginning to distinguish between exposure to AI demand and the ability to convert that demand into durable economics. That is a more mature question than whether AI usage itself continues to grow.
Open Models Are Accelerating the Pressure
The open-model transition makes this dynamic more visible. Vercel’s AI Gateway data recently showed open-weight models reaching approximately 62 percent of token volume on August 22, up from 28.4 percent roughly two months earlier and about 11 percent in April. These are figures from one platform rather than the entire AI industry, but the speed of the shift is notable because it illustrates how quickly enterprises are becoming comfortable distributing workloads across different classes of models.
Customers are learning something logistics managers learned long ago: not every movement requires premium service. You do not ship every load by air, give every SKU the same inventory policy or assign the most expensive resource to every task simply because it is technically capable of performing it. The same logic is beginning to apply to AI.
Enterprises can route difficult tasks to expensive frontier models while sending repetitive, lower-value or highly specialized workloads to cheaper models. That is good architecture, but it is also price pressure. As switching becomes easier, the model itself increasingly becomes one component within a larger decision architecture rather than the architecture itself. That changes where the economic moat resides.
The Value May Move Up the Stack
Consider a logistics company using AI to manage exceptions. The model may analyze late shipments, weather, inventory availability, customer commitments and transportation alternatives, then recommend that an order be reallocated, a shipment expedited or a customer promise changed. Suppose the model call costs 20 cents today and two cents three years from now. The model provider has experienced severe unit-price compression, but the logistics operator has not necessarily lost anything.
In fact, the logistics operator may gain considerably. If the AI avoids a $5,000 expedite, prevents a stockout or allows one planner to manage twice as many exceptions, the economic value exists primarily in the operating outcome rather than in the token used to generate the recommendation. The falling price of the underlying intelligence therefore increases the potential return available to the enterprise consuming it.
This is where the AI economics discussion becomes particularly relevant to enterprise logistics. Falling model prices could transfer economic value away from model providers and toward companies capable of embedding inexpensive intelligence into valuable workflows. The model becomes cheaper while the decision becomes more valuable.
Architecture Becomes the Moat
This suggests that enterprises should be careful about defining an “AI strategy” around access to a particular model. Model leadership can change, and prices can change even faster. An enterprise architecture built tightly around a single provider may eventually look like a transportation network designed around one carrier regardless of lane, service requirement or price. It may work, but it gives up much of the flexibility required to optimize the system over time.
The more durable architecture is likely to separate the business problem from the intelligence resource used to solve it. Understand the decision, assemble the required context, define the constraints and determine the acceptable action. Only then should the enterprise route the problem to the model — or combination of models — capable of solving it at the appropriate performance, risk and cost level.
That is not simply AI adoption. It is AI orchestration, and it looks remarkably similar to other logistics optimization problems. The objective is not to maximize utilization of a particular asset but to select the right resource for the right problem while optimizing the performance of the overall system.
Intelligence Is Becoming a Variable Cost
The larger economic change may be that machine intelligence is becoming a purchasable input whose price declines rapidly. For most of industrial history, intelligence has been expensive because analytical capacity was constrained by the number of skilled people available to perform the work. AI begins to relax that constraint by turning portions of analytical work into a scalable operating input.
If the cost of a useful unit of machine reasoning continues falling, companies can economically apply intelligence to thousands of decisions that previously could not justify human analysis. Shipment prioritization, carrier selection, inventory rebalancing, appointment scheduling, exception resolution, warehouse labor planning, supplier-risk analysis and customer-response generation are all candidates. Individually, many of those decisions may appear too small to justify significant analytical effort. Collectively, they determine a substantial portion of supply-chain performance.
Every one of these activities can potentially consume enormous quantities of tokens while producing economic value far larger than the cost of those tokens. This is why collapsing AI prices are not necessarily bearish for AI adoption. They may instead be extraordinarily bullish for the users of AI because lower intelligence costs expand the number of operating decisions where machine reasoning becomes economically rational.
The Second Half of the AI Trade
The first phase of the AI boom rewarded scarcity. There were too few advanced GPUs, too little compute, too few frontier models and too little capacity. Scarcity created pricing power and directed enormous amounts of capital toward the companies capable of supplying those constrained resources.
The next phase may reward orchestration. Models will proliferate, intelligence will become cheaper, enterprises will learn to switch among providers and open-weight systems will handle an increasing share of routine workloads. Infrastructure costs will continue to matter, but customers will become much more disciplined about what they are willing to pay for a unit of intelligence and much more sophisticated about matching different models to different operating requirements.
That does not mean the AI boom is over. It means the economics are maturing. The winners in logistics will probably not be the companies that consume the most AI; they will be the companies that turn increasingly inexpensive intelligence into better operating decisions at scale.
That is a very different metric. Tokens are an input, while the decision is the product. The economic value ultimately belongs to whoever can use that decision to improve the performance of the system.
Featured Logistics Research
Explore Logistics Viewpoints research on the technologies, architectures, and operating models shaping modern logistics and supply chains.
Featured White Papers
2026 Market Maps
Independent ARC Advisory Group research and Logistics Viewpoints analysis.