

Barry Norris: My Three-year Epiphany That Led To This Year's Double-digit Gains
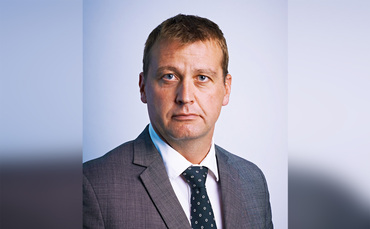
Looking beyond stockpicking and focusing more on portfolio management, as well as holding a more diversified portfolio of smaller positions in the short book, means Argonaut's Barry Norris is confident his Absolute Return fund will outperform both through the current coronavirus pandemic and over the next market cycle.
The FP Argonaut Absolute Return fund, which Norris has managed since 2009, is up 22.6% year-to-date at time of writing (23 March), having more than doubled the second-best performing fund in the IA Targeted Absolute Return sector over this time frame.
As a point of comparison, the MSCI World and FTSE 100 indices are down 18.1% and 30.4% respectively, according to data from FE fundinfo.
"If you look at my returns year to date, you might just think I made a massive punt on the market going down. But actually we have been up during 80% of the days this year, which means we have been making money on good days as well as bad days," Norris explained.
Dickie Hodges: Why equity markets will hit 'all-time highs' again by year-end
The manager said his fund - a long/short portfolio of global equity stocks - currently has a net long exposure of 100% and a 75% short exposure, although the portfolio has made gains of 60% alone from its short stocks, which is why the vehicle has achieved double-digit gains in 2020 so far.
Norris said the ultimate goal is therefore to ensure the portfolio is "uncorrelated to markets, not negatively correlated".
"I do not want to run a product that people think is always going to go up when the market goes down. By nature I am a fairly optimistic person; I do not want to be somebody who is betting on the end of the world all the time," he said.
"That said, I do think there is long alpha and short alpha, and if you can combine the two with a modest net long exposure, then you should beat the market - even a bull market - with a return profile that is not reliant on market beta."
Peter Hargreaves: Expensive tech stocks now look 'cheaper'
While the fund is performing well year-to-date, and has achieved strong gains during eight years of the last decade, 2016 was a difficult year for Norris. His fund fell more than 25%, making it the single-worst performing fund in the Investment Association universe.
"That was a very painful time, and there were a number of aspects to this," Norris explained.
"Firstly, a lot of the money that we lost in that year was shorting stocks such as banks and commodities which, since 2016 have hit new lows.
"I concluded that we were right in our analysis of the companies, but we were not prepared to be wrong in the short term.
"Initially I thought I was wrong, but actually I was right about the stocks but wrong about markets. What drove markets that year was a big top-down reflation trade where analysis of individual stocks did not matter very much.
"After that year, I was pretty aware that nobody remembered I returned 80% over the previous three years. I was therefore determined to make good any losses for people that had bought in more recently and really suffered."
2017 was a good year for the fund as it returned 18%. Then in 2018, the fund lost 11.7%. The fund fared well again in 2019 with a 12.8% return, but Norris was determined to make its return profile more consistent and "less lumpy".
He decided the solution was to look beyond stockpicking and focus on portfolio management, as well as to increase diversification and reduce the position sizes in his short book.
"A lot of attention gets paid to what makes a good stock and rightly so, but I had to become a lot better at the portfolio management aspect," Norris said.
"By that, I mean blending the different stocks that we have in the portfolio in order to not only diversify risk, but ensure the volatility and correlation is manageable and produces a more consistent outcome in terms of fund return.
"On the short book, you want to maintain your position size - otherwise you basically keep doubling up on the same bet."
He said this will likely mean the fund will continue to perform well, regardless of sudden downturns or unexpected market movements.
In the current crisis, for example, he pointed out that nobody could have predicted that gold would sell off alongside equities, as investors scrambled to liquidate their investments.
"I implemented this new way of thinking at the start of this year. Because to be honest it probably took me three years to think deeply enough about it and come to the conclusion as to what went wrong," he admitted.
"You can be the cleverest fund manager in terms of thinking ahead and what is fundamentally going to happen, but these liquidity squeezes are much more difficult to plan for.
"It is a trap that we have avoided spectacularly year to date. That is largely a feature of better portfolio management and diversification."
What A Rising VIX Means For Pension Funds
Wall Street’s latest selloff has moved beyond a technology-sector wobble and become a broad market event. The Nasdaq C... Read more
Behaviour Cannot Fix A Portfolio Construction Flaw
A Retiree Shouldn't Be Asked to Behave Their Way Out of a Portfolio Construction Problem Why behavioural coaching shoul... Read more
Behavioural & Retirement Portfolio Resilience
Behavioural Survivability and Retirement Portfolio Resilience Why the lived experience of market recovery matters as mu... Read more
Australia's Rate Rise Bites: Highest In 15 Years
The Reserve Bank of Australia has lifted interest rates to their highest level since 2011, and its governor admits the w... Read more
October Retirement Portfolio Resilience Assessment
Markets stabl Read more
Gyrostat September Retirement Portfolio Resilience Assessment
September Retirement Portfolio Resilience Assessment Markets have fallen. The price of risk has risen. ... Read more