Insurance AI Moves From Pilots To Production As Buyers Demand Proof
AI specialists took 83.2 per cent of InsurTech funding in the third quarter, and Guidewire has agreed to pay up to $2.1bn for hyperexponential. The harder test is whether insurers can prove the returns.
When Guidewire agreed on 28 October to buy hyperexponential, the London-based underwriting and pricing platform known as hx, it put a price on the idea that AI will sit at the centre of how commercial risks are assessed and priced. Guidewire, which serves more than 570 property and casualty insurers, will pay $1.7bn in cash and up to $400m more if recurring revenue targets are met, according to FinTech Global. hx says its software has supported underwriting decisions on more than $75bn of annual commercial premium.
The deal lands as capital narrows towards a single theme. The question for insurers, MGAs and brokers is no longer whether to use AI, but whether the tools they buy can show results that survive scrutiny from finance directors, auditors and regulators.
Capital follows the AI label
Gallagher Re's latest Global InsurTech Report found that global InsurTech funding fell 44.6 per cent from the previous quarter to $1.36bn in the third quarter of 2026. Yet AI-focused companies raised $1.13bn across 72 deals, or 83.2 per cent of the total, Reinsurance News reported. The headline fall reflects fewer very large rounds: funding from rounds of $100m or more dropped from $1.67bn to $660m, while the number of deals barely moved, at 104 against 107.

Source: Gallagher Re, Global InsurTech Report, Q4 2025 to Q3 2026 editions, as reported by Reinsurance News.
Andrew Johnston, global head of InsurTech at Gallagher Re, framed the real test plainly: "It is whether InsurTechs are solving real business problems that insurers, reinsurers and their clients are prepared to pay for."
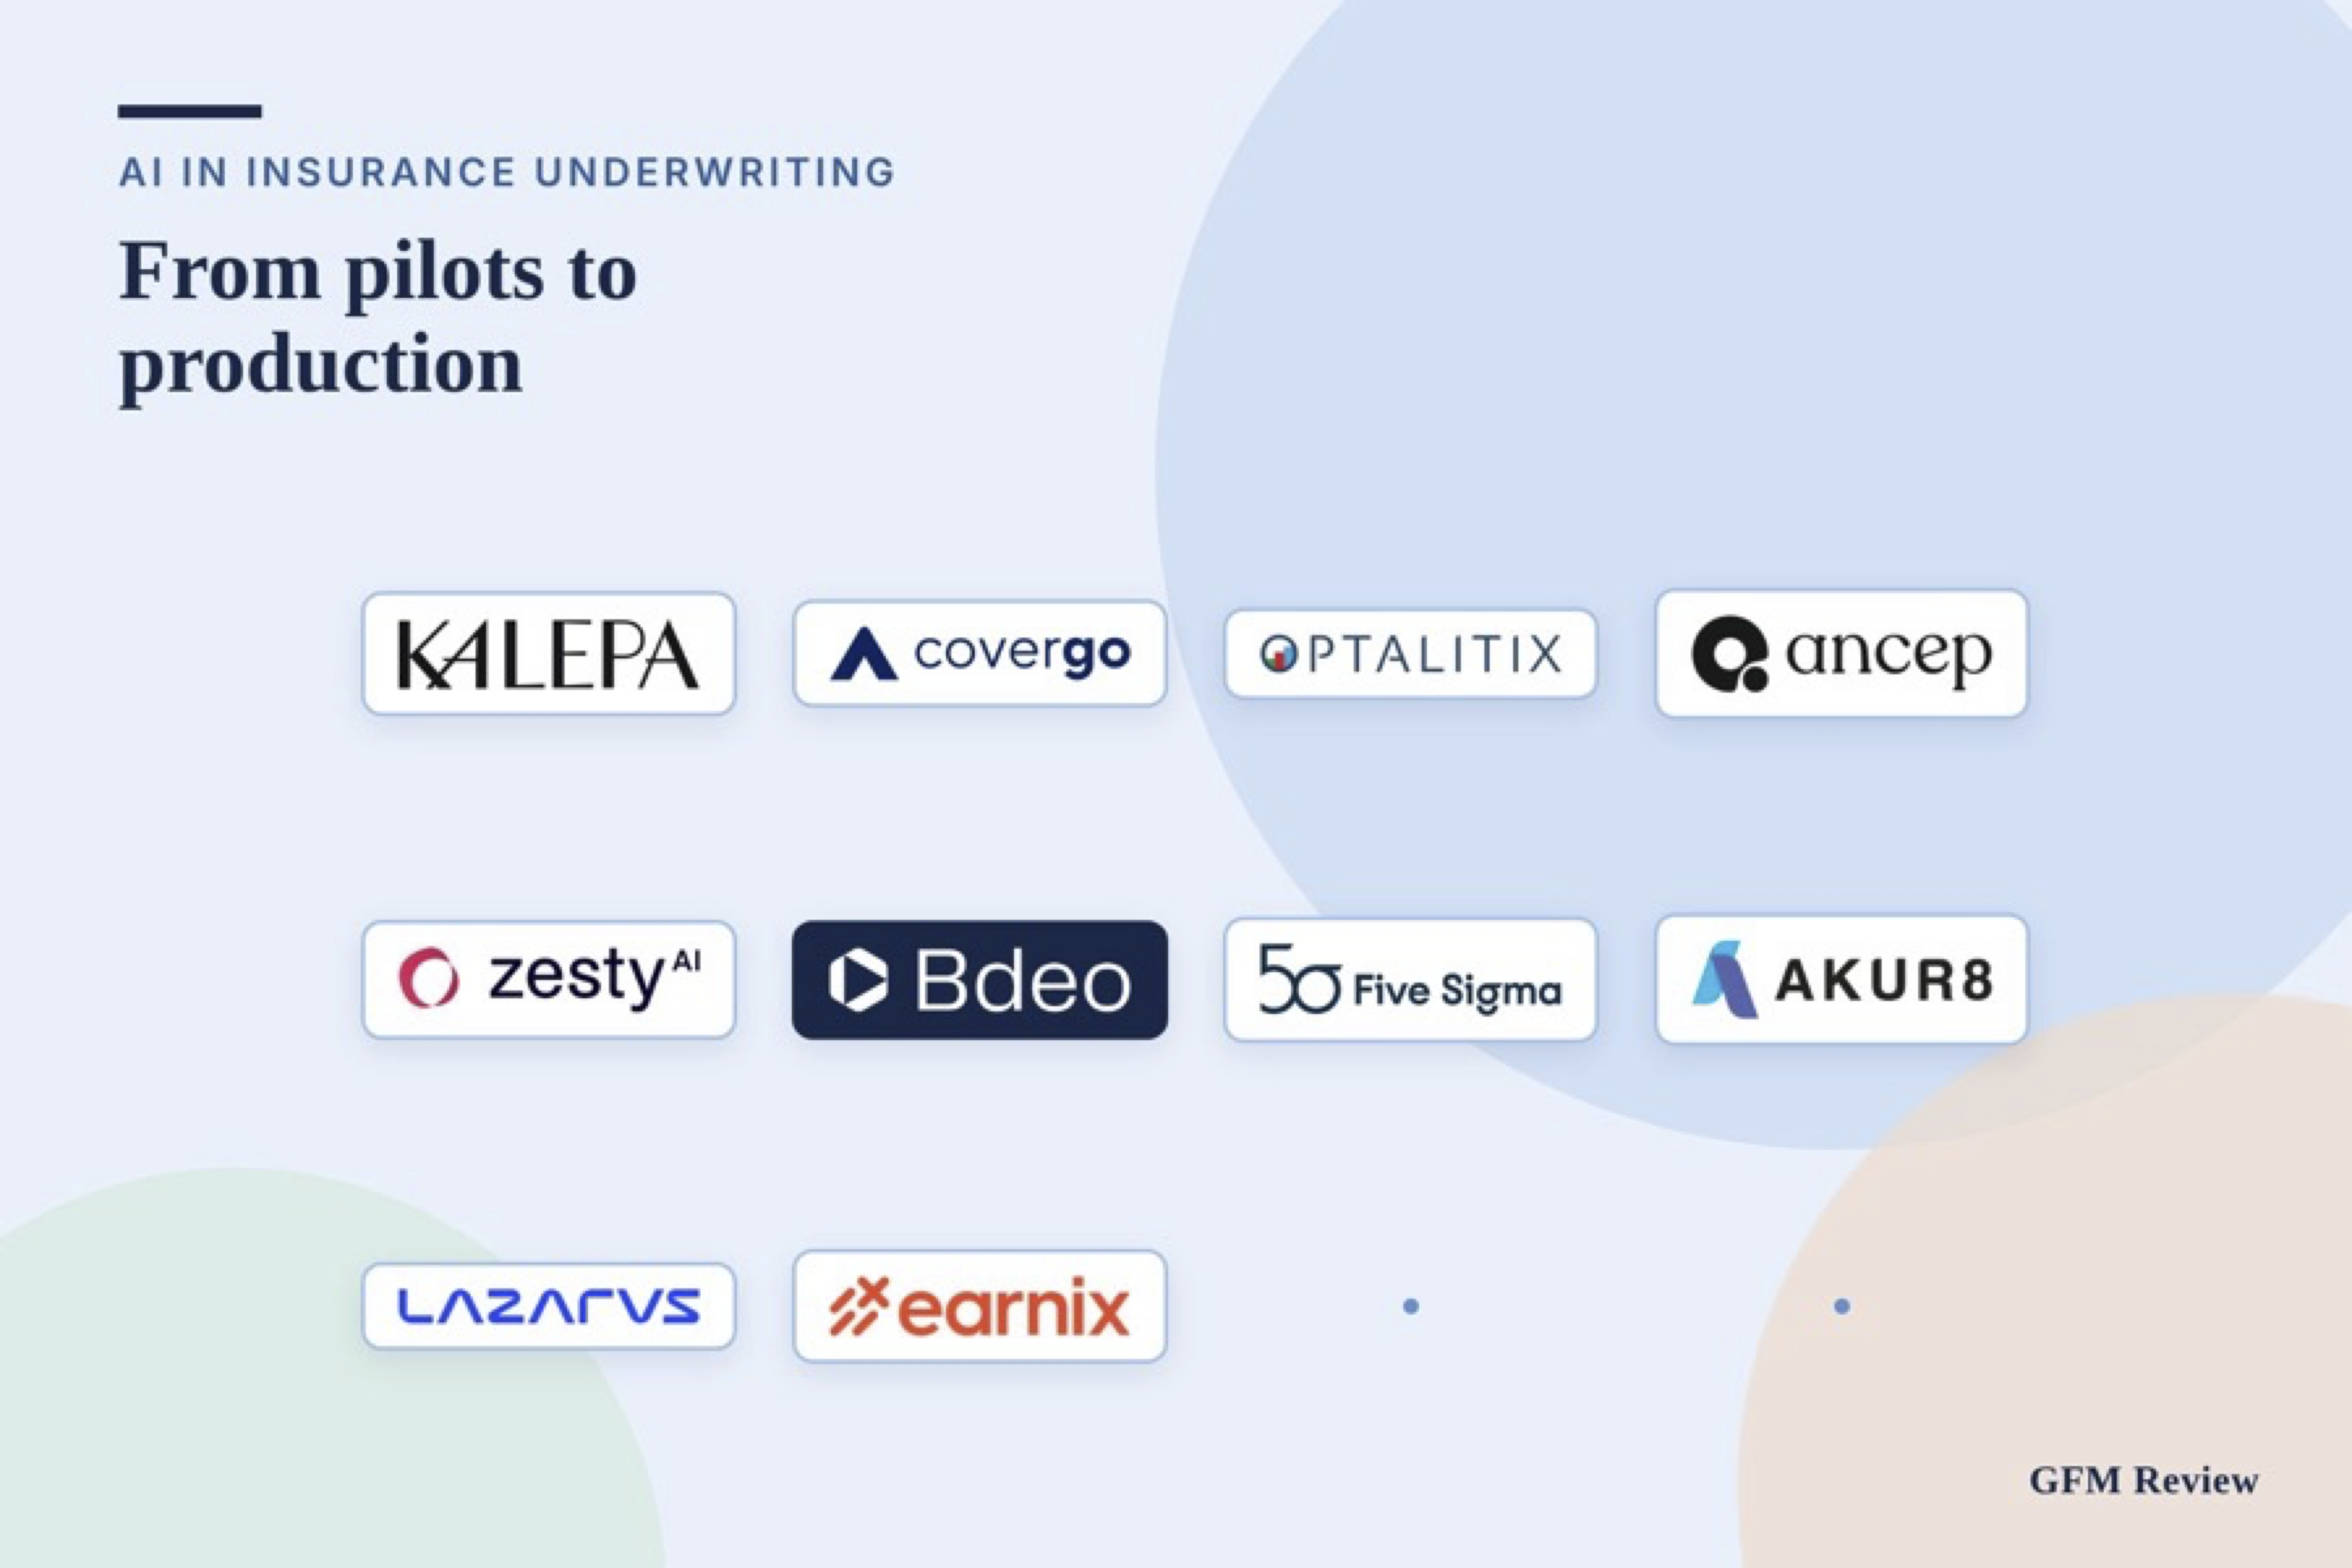
Recent rounds show where investors are placing that bet. Kalepa, a New York underwriting platform whose clients include W. R. Berkley and Bowhead Specialty, raised a $75m Series B at a $470m valuation, led by Updata Partners.Lazarus AI raised $43m for its production AI for regulated organisations, with QBE and State Farm Ventures among its backers, a sign that insurers are prepared to fund the suppliers they may later rely on. London's Ancep raised $8.5m, led by Creandum with Kleiner Perkins participating, for agents that help brokers place smaller commercial risks. CoverGo, a core platform for health, life and P&C insurers, announced a $6m first close of a Series B1 round led by Betatron Venture Group and says it serves 25 institutional clients in 15 countries.
Why a soft market raises the stakes
The commercial logic is sharpened by the pricing cycle. Marsh's Global Insurance Market Index showed commercial rates falling 5 per cent in the third quarter, the ninth consecutive quarterly decline, with property down 10 per cent. With premium per risk falling, insurers protect margins by cutting the cost of handling each submission and claim, and by selecting and pricing risks more precisely.
That is where much of the specialist activity sits. Akur8, whose Deploy rating engine was named a Luminary by Celent in its 2026 rating engine reports, says more than 15 insurers in 12 countries use the product to push rate changes from actuarial models straight into a live rating service. Earnix was chosen by In The Car, which builds embedded motor insurance for manufacturers and dealers, to support its expansion from two US states into 18 more markets. Optalitixhas added agentic functions to its Optalitix Quote platform that review claims history, flag irregular loss data and check quotes against authority limits, while insurers keep sign-off and every action is logged.
Regulatory acceptance is becoming a competitive asset in its own right. ZestyAI said on 9 November that its Z-WATER model for non-weather water damage had been accepted in Minnesota and Maryland, taking it to 22 US states, and that its models had passed 500 regulatory approvals by September.
Claims is the other pressure point. Five Sigma has agreed to connect its claims platform with Amarillo's Fusion delegated authority reporting system, so that claims data flows into binder reporting without being rekeyed. Madrid-based Bdeo, which says it works with more than 50 insurers in over 25 countries, including eight of Spain's 10 largest motor insurers, has moved a Vonage network service into production to keep claim videos clear enough for its damage assessment models.
Adoption is broad, proof is thin
The vendors' numbers deserve caution. Kalepa reports that customers have achieved 30 to 60 per cent more premium per underwriter and cut quoting times by 58 per cent; Ancep estimates that up to 30 per cent of the risks brokers receive are too small to justify the work involved. These are company figures, not audited outcomes.
Independent surveys point to a gap between use and evidence. Moody's Ratings surveyed 58 North American insurers and brokers and found about two thirds running AI broadly or in multiple production uses, yet only 41 per cent quantify and track benefits for individual use cases. KPMG found that no insurer in its survey had fully redesigned underwriting around AI, and only 11 per cent said their data foundations were ready to scale beyond pilots. The IBM Institute for Business Value put the share of insurers achieving consistently high returns at scale at 12 per cent.
Data is the binding constraint. AutoRek's 2026 insurance report found that insurers use an average of 17 data sources in their premium processes alone, and 39 per cent named fragmented data as a barrier to AI.
Regulation adds a further test. Under the NAIC's model bulletin, adopted by 24 US states by March 2025, insurers must keep a written AI programme covering governance, risk controls and oversight of third-party vendors, so responsibility for a supplier's model stays with the carrier. In Europe, the deadline for the AI Act's high-risk obligations has been pushed back to 2 December 2027, which delays but does not remove the compliance work.
What to watch
The first marker is Guidewire's December earnings call, when it is due to update guidance. It expects hx to add at least 650 basis points to annual recurring revenue growth in its 2027 financial year, and the deal is due to close in the second quarter of that year. Those targets will show how quickly carriers pay for AI underwriting at scale.
The second is Gallagher Re's fourth-quarter data. A rebound in large rounds would suggest investors still see room for independent specialists; continued concentration would point to more consolidation.
The third, and the one that matters most to buyers, is whether insurers begin to publish measured gains in loss ratios, expense ratios and quote turnaround. Until they do, the sector's valuations rest more on expectation than on evidence.
People Power: Building The Future Of Insurance One Career At A Time
The insurance industry is at a pivotal point. As emerging technologies reshape underwriting, claims processing, and cust... Read more
Private Equity's Great Divide: Is The Future Insurance-Funded Or Fee-Driven?
A fundamental shift is taking place at the top of the private equity industry. While firms like Blackstone remain commit... Read more
Japan's Next Battleground: The Insurance Sector Under Activist Pressure
Farallon’s push at T&D Holdings marks a shift in focus for activist capital targeting Japan’s untapped insurance... Read more
Cover And Conflict: Tensions Rise Between Insurers And Litigation Funders
Burford’s clash with Chubb signals a deeper rift in the legal-financial ecosystem A high-profile dispute between li... Read more
Underwater And Uninsured: How Climate Risk Is Reshaping The US Mortgage Market
As climate change intensifies, its effects are no longer confined to coastlines or news reports on extreme weather. In t... Read more
When The Raters Get Rated: What The Fitch–Kroll Feud Says About Oversight And Accountability
In a rare and unusually public confrontation between two of America’s credit rating agencies, a recent feud between Fi... Read more